WSA delivered 2% organic growth and improved profitability in the 2025/26 financial year
18 Nov 2026
Lynge, Denmark – November 18, 2026 – WSA, a leading hearing healthcare group, today announced results for the financial year 2025/26 (October 1, 2025 – September 30, 2026), showing organic revenue growth of 2%, and an EBITDA margin improvement of 1%-point, in line with the guidance.
Jan Mäkelä, CEO of WSA, says:
In the financial year 2025/26, we remained disciplined in executing our strategy and advancing innovation in personalized hearing care, and on driving profitability. We delivered 2% organic revenue growth and improved the profit margin in line with our guidance. Our consumer-facing businesses performed strongly, while the timing of product launches impacted our wholesale business.
At WSA, we believe that better hearing starts with recognizing that no two people hear the world in the same way. Understanding individual sound preferences opens up a new dimension in personalized hearing care. We have brought this approach to life through several significant innovations and product launches, which have been very well received in the market.
Our outlook for 2026/27 is impacted by the non-renewal of a large US managed care contract, as previously announced. Excluding this impact, we expect revenue to grow in line with or above the market, with continued improvement in profitability. Although the non-renewal of the contract weighs on our near-term guidance, our disciplined strategy execution and competitive product portfolio provide a solid foundation for long-term profitable growth.
Highlights FY 2025/2026 (FY last financial year in brackets)
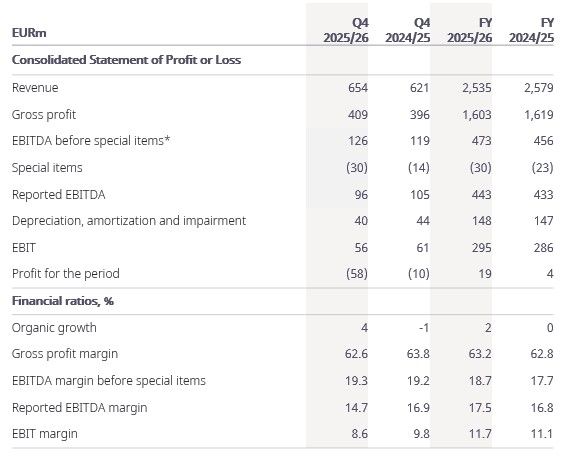
- WSA Group delivered organic revenue growth of +2% (0%) to EUR 2,535 million. Group reported revenue was -2%.
- The Wholesale business delivered organic growth of -3%, impacted by the timing of WSA’s product launches. Growth momentum improved toward the end of the year.
- The Consumer-facing business delivered +7% organic growth driven by Managed Care, Retail and Online businesses.
- Revenue growth was mixed across geographies with +3% organic growth in Americas, 0% organic growth in EMEA, and 0% organic growth in APAC.
- EBITDA before special items increased to EUR 473 million (EUR 456 million).
- EBITDA margin before special items increased to +18.7%, an improvement of 1.0%-point compared with last year, in line with our guidance.
- WSA launched Signia MaX, the world’s first AI hearing aid platform with four Deep Neural Networks, designed to help wearers stay connected in complex and noisy listening environments, and Widex Allure AI with Clarity Boost, which combines Widex’ natural everyday sound with on-demand AI-powered support for clearer conversations in noisy environments.
- WSA announced changes to its Board of Directors. Adam Westermann, co-owner and board member of T&W Medical is stepping down as Vice Chair of the board. Julian Tøpholm, co-owner and board member of T&W Medical, is becoming the new Vice Chair, representing the Tøpholm and Westermann families.
Highlights Q4 FY 2025/26 (Q4 last financial year in brackets)
- In Q4, WSA delivered organic revenue growth of 4% (-1%) to EUR 654 million. Group reported revenue increased 5% due to currency tailwinds.
- EBITDA before special items was EUR 126 million with a margin improvement of 0.1%-points.
- The Wholesale business delivered 0% organic growth in Q4, impacted by the timing of WSA’s product launches.
- In Q4, the Consumer-facing business delivered +8% organic growth driven by Managed Care, Retail and Online businesses.
- Revenue growth was mixed across geographies in Q4 with +5% organic growth in Americas, +3% organic growth in EMEA, and +1% organic growth in APAC.
Outlook Financial year 2026/2027
For the financial year 2026/27, WSA expects -2 to +2% organic revenue growth. The EBITDA margin (before special items) is expected to decline by around 2%-points versus financial year 2025/26 (18.7%).
The outlook is based on the following key assumptions:
The volume growth in the hearing aid market is expected to be in the range of 3-4%. Some volatility is expected due to the ongoing uncertain macroeconomic environment.
The revenue growth outlook is supported by WSA’s competitive product portfolio, including the recent launches of Signia Max and Widex Allure AI and the launch of additional form factors.
In August 2026, WSA announced that a contract with a large US Managed Care customer will not be renewed after it expires on January 1, 2027. This is now estimated to have an impact of around 5%-pts on group revenue growth and around 3%-pts on group margin for FY2026/27. Excluding this impact, WSA expects revenue growth in line with or above the market and continued improved profitability.
The EBITDA margin outlook is supported by cost reductions made in FY 2025/26 as well as ongoing optimization and prudent cost management.
For the full FY 2025/26 Annual Report, please go to WSA.com/investors/reports